How telcos can capture value from the AI token economy
Author
How telcos can capture value from the AI token economy
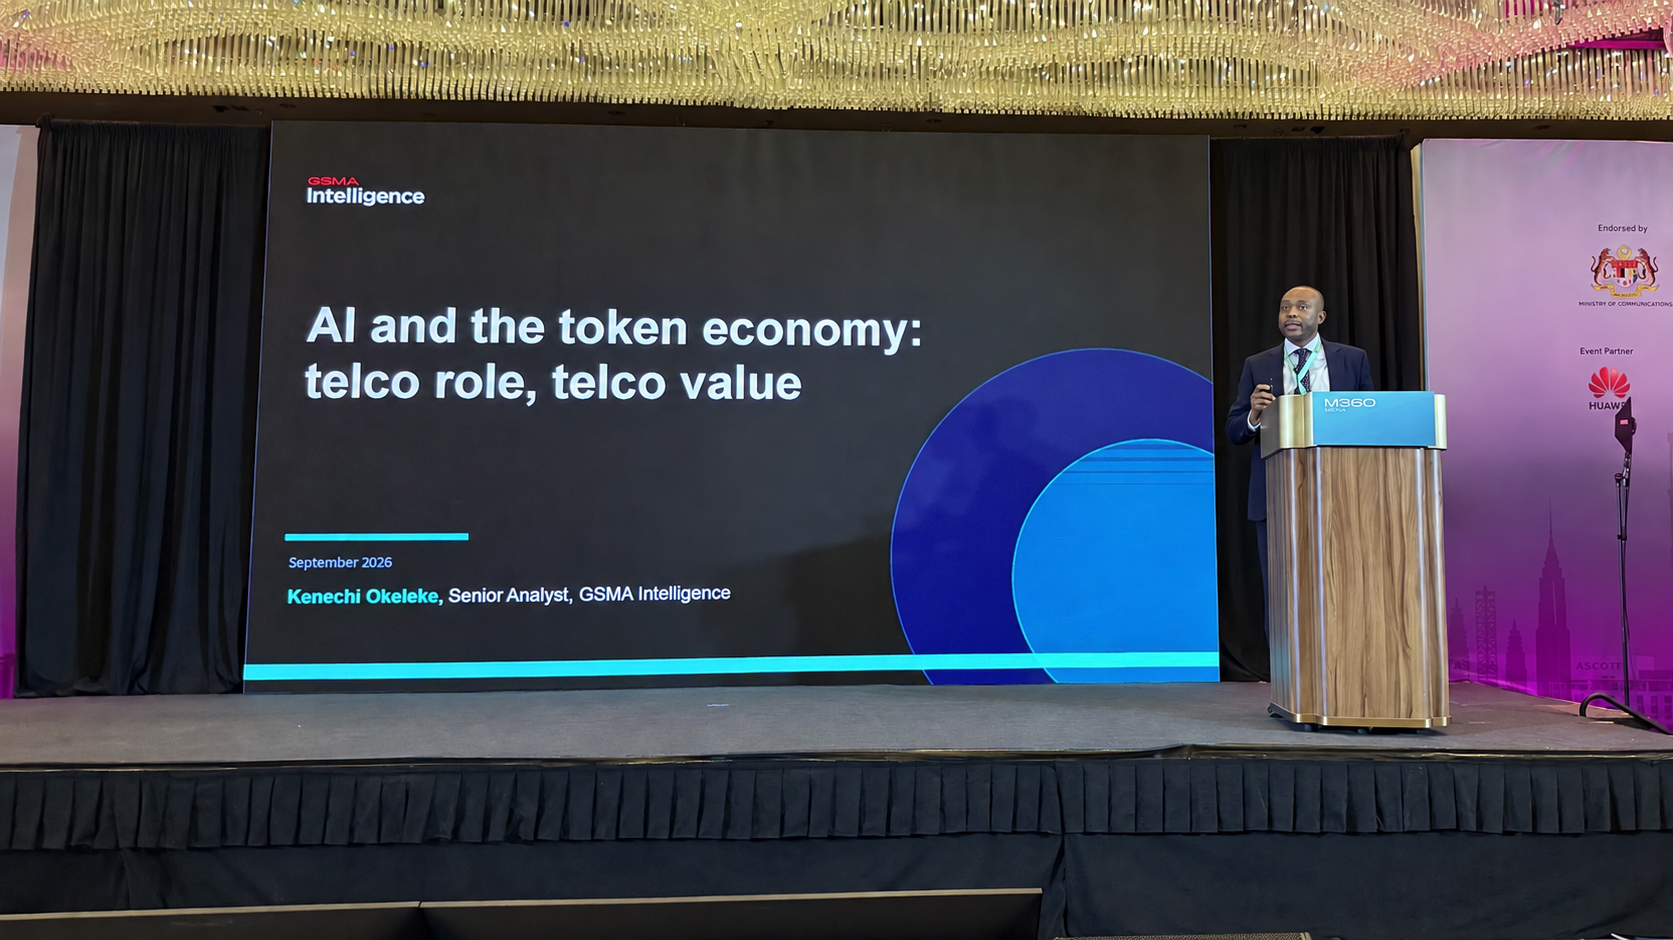
AI discussions in telecoms have largely focused on efficiency and internal transformation. A new opportunity is now emerging around AI consumption, as enterprises and consumers increasingly use AI-powered applications, agents and workflows. Tokens are becoming the unit for measuring, managing and monetising this activity, creating scope for telcos to move beyond connectivity and help customers access, govern and optimise increasingly complex AI services.
From gigabytes to tokens: understanding the shift
Telos have always found ways to turn digital consumption into revenue. First came voice minutes, then gigabytes in the smartphone era. AI is introducing the next unit of consumption: the token. But tokens are not simply the new gigabytes. While a gigabyte measures network traffic, a token reflects AI processing - and its value changes depending on the model, the complexity of the task and whether it covers input, output, cached context or reasoning.
For telcos, that creates a familiar challenge with an added layer of complexity. People never thought about streaming a film in megabytes, and they are unlikely to think about creating content or running an AI agent in tokens. The winners will be the providers that make the underlying mechanics invisible and turn AI consumption into simple propositions built around useful applications, clear outcomes and seamless experiences.
Telcos are expanding across the AI value chain
So where are telcos placing their bets? GSMA Intelligence research points to activity across three layers of the AI value chain. At the infrastructure layer, operators are putting their data centres, cloud assets, fibre networks and edge infrastructure to work through AI factories, sovereign AI platforms and GPU-as-a-service. At the model layer, some are developing or co-developing foundation models tailored to local languages and market needs.
The solutions layer is where momentum is strongest. Telcos are rolling out enterprise copilots, conversational AI, productivity tools and industry-specific applications—and more than 200 operators worldwide are already active in this space, making it the most common route into AI monetisation. Asia Pacific is leading the shift, accounting for 43% of global telco participation at the infrastructure layer and 38% at the model layer.
China provides an early commercial test
China offers a glimpse of what direct AI monetisation could look like for telcos. Average daily token use surged from around 100 billion at the start of 2024 to 140 trillion by March 2026. Much of that growth has come from AI agents and coding assistants, which can trigger long chains of model interactions from a single prompt.
The country’s three major telcos are already testing different ways to turn that demand into revenue. China Telecom bundles access to AI models with connectivity and cybersecurity for consumers and enterprises. China Mobile combines AI tokens with cloud PCs and AI agent capabilities in regional packages. China Unicom, meanwhile, is exploring a credit-based approach that makes it easier to manage token use across multiple models.
China’s experience comes with an important caveat: context matters. Its telcos benefit from substantial cloud businesses, heavy investment in AI infrastructure and a broad ecosystem of open-weight models. That makes these initiatives valuable proof points, but not ready-made templates for every market. Operators elsewhere will need approaches that reflect their own infrastructure, customers and competitive conditions. Even so, China shows that telcos can do more than connect users to AI applications but can also generate revenue from AI consumption.
The bigger prize lies in the control layer
Simply reselling tokens will be easy to replicate and difficult for telcos to defend. The more compelling opportunity is what GSMA Intelligence calls the control layer. As enterprises spread their AI use across multiple models and providers, managing that activity quickly becomes complicated. They need to decide which model to use, where to route each workload, how to keep costs under control and how to meet governance requirements.
That is where telcos can play a bigger role: not just selling AI capacity but helping customers manage how it is consumed. In practice, the control layer is likely to develop in three stages:
- Model aggregation: bringing multiple AI models together behind a single interface, API and bill.
- Intelligent routing: selecting the best model for each task based on factors such as cost, quality, latency, availability and regulation.
- Workflow optimisation: helping customers turn AI use into measurable cost savings or productivity gains, and giving providers a share of the value created.
Early examples show what this could deliver. China Mobile says its MoMA platform can reduce token costs by 20–30% through intelligent routing, caching and context reuse. AT&T has reported savings of up to 90% from its internal AI gateway, indicating that telcos can prove the model inside their own businesses before taking it to customers.
Where telcos can win
So where can telcos genuinely stand out? The answer lies in the assets they already have: trusted customer relationships, billing and identity capabilities, local support, security and compliance expertise, connectivity, regulatory knowledge and sovereign or distributed infrastructure. These strengths make the control layer one of the most promising positions for telcos in the AI value chain.
Capturing that opportunity will require focus. Telcos need to choose a credible role in the AI value chain, build the right capabilities and form partnerships without slipping into low-margin resale. They should develop the control layer before taking token-based offers to scale. At the same time, operators must prepare their networks for more distributed - and potentially more uplink-intensive - AI traffic, using network APIs and edge capabilities to combine AI consumption with differentiated connectivity.
The window is narrow
The opportunity is real, but the window to act is narrowing. The AI economy is moving faster than the telecoms industry is used to, and hyperscalers, cloud providers and AI-native companies are already building the platforms and control layers that will shape access to AI services. Telcos bring powerful advantages, including trusted customer relationships, local presence, regulatory expertise, connectivity and distributed infrastructure, but they cannot assume those strengths will remain uncontested.
Tokens may become a defining measure of AI consumption, but they are only the starting point. The bigger prize lies in making AI easier to access, safer to govern and more cost-effective to use. That gives telcos a chance to move up the digital value chain and participate directly in monetising AI consumption. In the end, the winners may not be those selling the most tokens, but those helping customers get the greatest value from AI.
The choice is becoming clear. Telcos that move now can help shape how AI is distributed, governed and used. Those that wait risk being left with the connectivity role while companies controlling the intelligence layer capture more of the value. The token economy is already taking shape, and how operators respond could define the next phase of telecoms growth.
How can we support you?
Get in touch
Contact the GSMA Intelligence support team for help with your account, subscriptions, or access to reports and insights.
Newsletter
Subscribe to the GSMA Intelligence newsletter for the latest industry news and insights, delivered to your inbox.

- 200 reports a year
- 50 million data points
- Over 350 metrics
How can we support you?
Get in touch
Contact the GSMA Intelligence support team for help with your account, subscriptions, or access to reports and insights.
Newsletter
Subscribe to the GSMA Intelligence newsletter for the latest industry news and insights, delivered to your inbox.